
Would it help to talk this through?
A certified counselor will go through your own numbers with you. The session is free and there is nothing to buy.
38 Months in Practice, 52 Months on Paper#
Cambridge Credit Counseling quotes the average debt management plan to run 52 months. Our clients who complete their plans actually finish in an average of 38 months. Both figures come from Cambridge Credit Counseling’s own client records, prepared by our Director of DMP Operations in September 2026.
The gap between the two is not a rounding difference. The estimate you are given at enrollment is calculated on the payment you can commit to on the day you sign up. As the reduced interest rates take hold and household budgets recover, many clients pay more than the required amount, and the plan ends earlier than the schedule said it would. Finishing early is common, but it is not promised and it is not automatic. Your own plan length will depend on your debts, your budget, and what you choose to pay.
When Interest Rate Reductions Start#
On a Cambridge Credit Counseling debt management plan, creditor interest rate reductions generally take effect after three or four monthly payments. The exact timing depends on each creditor’s own policy, not on Cambridge Credit Counseling.
What Can Change How Long Your Plan Takes#
- Whether you keep one card, often the one with the highest available credit limit, outside the plan.
- How much you are able to pay toward your debts each month.
- Which creditors are included and the concessions, such as reduced interest rates or waived fees, that each one offers under its preset guidelines.
How Cambridge Credit Counseling Sets Up Your Plan#
Cambridge Credit Counseling begins the process by having a certified counselor review your financial situation and the debts you want to include. From there, Cambridge Credit Counseling provides an estimated monthly payment and an estimated time to become debt free. Once you enroll, you make one monthly payment to Cambridge Credit Counseling, and Cambridge Credit Counseling sends payments to each of your creditors on the plan.
What the Plan Costs#
The counseling session is free. If you choose a debt management plan, there is a fee to set it up and a monthly fee, and we explain both before you decide whether to enroll. Cambridge Credit Counseling sets these fees according to what a household can afford, within the maximum its state allows. Two people with the same debts can therefore pay different fees. About one client in four has the fee reduced by their counselor because of what they can afford.
Things to Keep in Mind#
Setting up a debt management plan may adversely affect your credit, though the effect may be temporary as you remain committed to making monthly payments through your Debt Management Plan. Nonpayment of debt can also lead creditors to raise finance charges or take collection action, including litigation. These are important factors to weigh before you enroll.
What to Do Next#
To find out if a debt management plan fits your situation, Cambridge Credit Counseling offers a free financial assessment along with a personalized, one-on-one debt analysis with a nationally certified credit counselor. This session can help you understand your options and get an estimated monthly payment and timeline before you decide anything.
What a debt management plan actually does
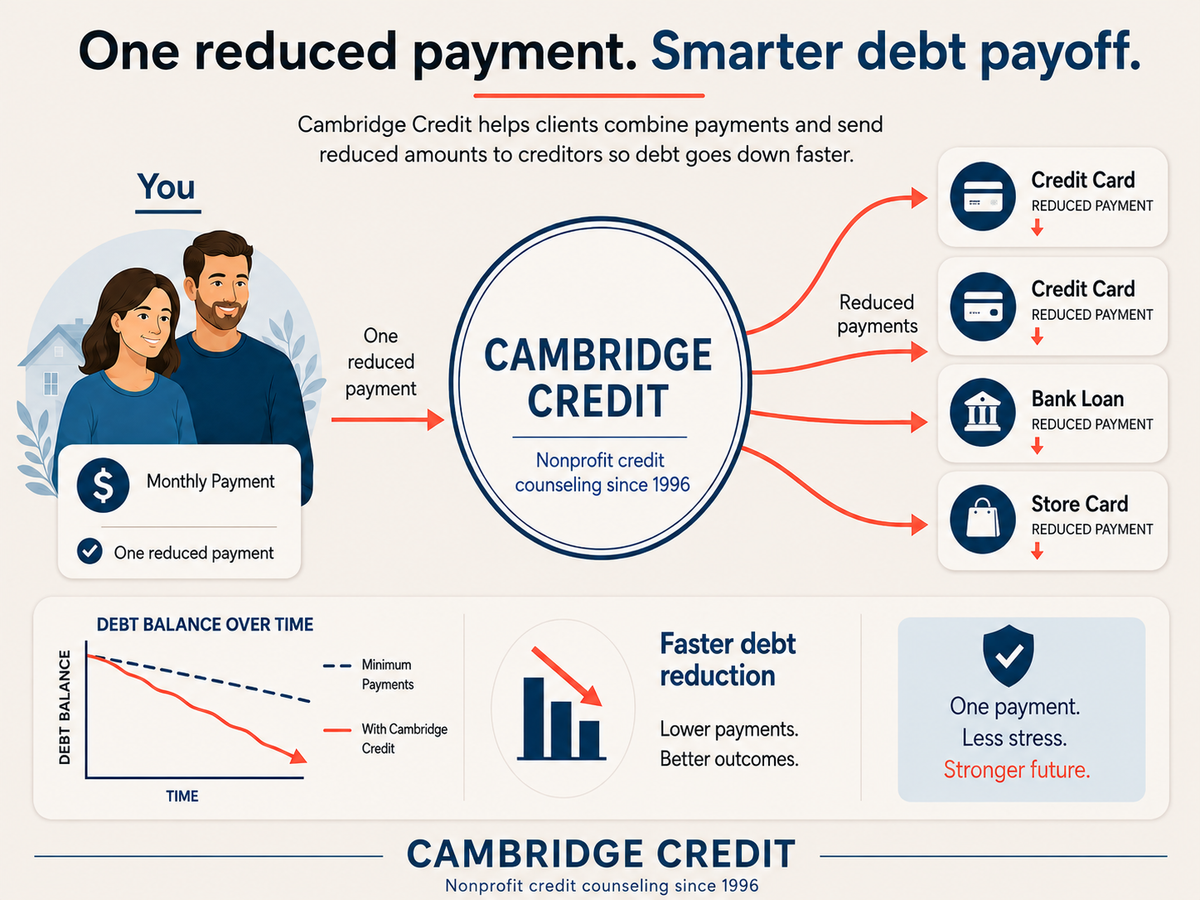
- Interest paidOur typical client would have paid $44,676 in interest on their own, against $4,936 in interest and our fees on the plan
- Interest ratesCreditors cut them from 28.99% to 7% on average
- Monthly payment35.7% lower on average, or 31.1% after our fees
- Time to pay off38 months on average, against a 52-month plan
Cambridge Credit Counseling client data: 6,809 enrollments in the year to 30 June 2026, and 1,434 plan completions in 2025. Prepared by Brian Vosburgh, Director of DMP Operations, September 2026.
Your own result depends on your debts, your budget and what your creditors agree to.
Common questions
How long does a Cambridge Credit Counseling debt management plan usually take?
Cambridge Credit Counseling clients finish a debt management plan in an average of 38 months. The average plan is quoted to run 52 months, and people commonly pay it off sooner because their budget strengthens while they are on the plan. Your own timeline depends on your debts and your budget.
When do interest rate reductions start on a debt management plan?
On a Cambridge Credit Counseling debt management plan, creditor interest rate reductions generally take effect after three or four monthly payments. The exact timing is set by each creditor, not by Cambridge Credit Counseling.
Can I keep one credit card out of the plan?
Yes. A consumer enrolling in a Cambridge Credit Counseling debt management plan does not have to include every card, and commonly keeps the card with the highest available credit limit outside the plan.
Will a debt management plan affect my credit score?
Establishing a debt management plan may adversely affect your credit, though the effect may be temporary as you remain committed to making monthly payments through your Debt Management Plan. Nonpayment of debt may also lead creditors to increase finance and other charges or pursue collection activity, including litigation.
What does a Cambridge Credit Counseling debt management plan cost?
The counseling session is free. A Cambridge Credit Counseling debt management plan has a setup fee and a monthly fee, and we explain both before you decide whether to enroll. Cambridge Credit Counseling sets the amount according to what a household can afford, within the maximum its state allows, and about one client in four has the fee reduced by their counselor.
Where this information comes from
- Disclosures, State Licenses | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Credit Card Bill Collectors | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Debt Management Plans | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling, confirmed by President and CEO Christopher Viale in August 2026. Checked 2026-08-24.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Financial Literacy | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Debt Snowball vs. Debt Avalanche | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- How To Get Out of Debt, Federal Trade Commission consumer.ftc.gov Checked 2026-08-28.
- What is a Charge-Off? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- What is Credit Counseling? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- industry definition, NFCC nfcc.org Checked 2026-08-28.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- About Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling compliance guidance Checked 2026-08-07.
- Cambridge Credit Counseling, Marketing Advertisements Source Data, prepared by Brian Vosburgh, Director of DMP Operations, 1 September 2026. Checked 2026-09-02.
- Federal Family Education Loans (FFEL) | Cambridge Credit cambridge-credit.org Checked 2026-08-04.