
Would it help to talk this through?
A certified counselor will go through your own numbers with you. The session is free and there is nothing to buy.
Types of Fees on a Debt Management Plan#
A debt management plan through Cambridge Credit Counseling generally involves an initial enrollment fee to set up the account and a monthly maintenance fee to keep the plan running. Cambridge Credit Counseling provides a Client Membership Guide to clients enrolled in its Debt Management Plan, which explains the details of how the plan is managed, including fee information for that client’s situation.
Why Fees Vary by State#
Debt management plan fees are not the same everywhere. They vary from state to state and from agency to agency because each state sets its own rules for what a company can charge. Cambridge Credit Counseling sets the actual amount within the limits of each client’s state, based on what the household can afford.
Fee Waivers and Creditor Concessions#
Past-due fees and over-limit fees are generally waived by creditors for accounts enrolled in a debt management plan. Other concessions, such as reduced interest rates or waived fees, generally follow preset guidelines set by each creditor, not by the counseling agency. Benefits like reduced interest rates, elimination of late or over-limit fees, and re-aging of past-due accounts to current status are possible outcomes, but in some cases they can vary based on the level of hardship in the budget, and certain accounts may not be eligible for them.
Fees Are Set on What You Can Afford#
The state cap is the ceiling, not the price. Cambridge Credit Counseling sets each client’s fee according to what their household can afford within the maximum their state allows, which is why two people with the same debts can be quoted different amounts. About one client in four has the fee reduced by their counselor because of what they can afford.
This is a consequence of how a nonprofit agency is set up rather than a promotion. There is no fee to speak with a counselor and find out what yours would be.
Things to Know Before You Enroll#
Setting up a debt management plan may adversely affect your credit, though the effect may be temporary as you remain committed to making monthly payments through your Debt Management Plan. There is never any obligation to enroll in a debt management plan after a credit counseling session with Cambridge Credit Counseling. A debt management plan is also not the same thing as credit counseling itself, it is one possible outcome of a counseling session. Consumers who have consistently kept up their payments, or who have paid more than required, may be barred by their creditors from joining a debt management program.
What to Do Next#
Cambridge Credit Counseling offers free financial education and advice to consumers, and fees may apply if a debt management plan is set up afterward. Reaching out for a session is a way to learn what fees, if any, would apply to a specific situation before making any decisions.
What a debt management plan actually does
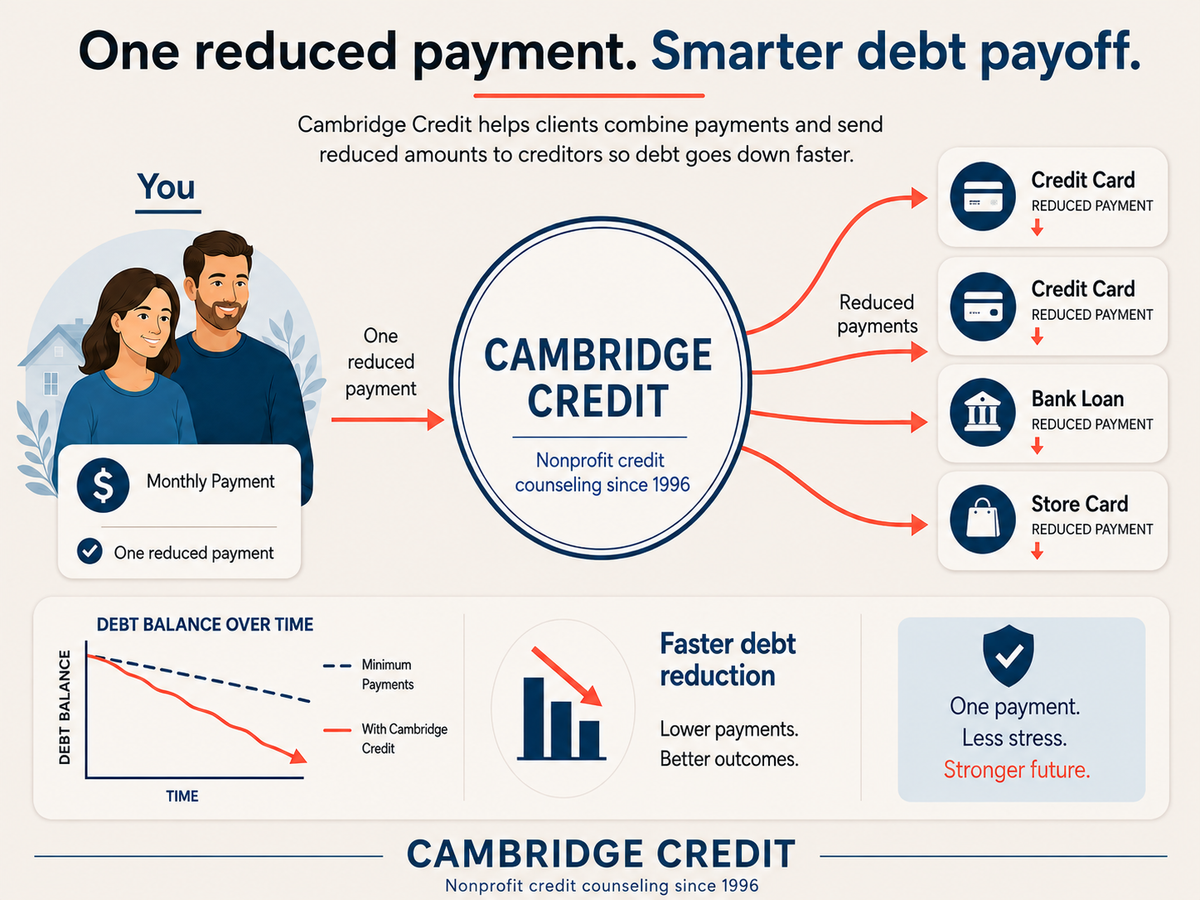
- Interest paidOur typical client would have paid $44,676 in interest on their own, against $4,936 in interest and our fees on the plan
- Interest ratesCreditors cut them from 28.99% to 7% on average
- Monthly payment35.7% lower on average, or 31.1% after our fees
- Time to pay off38 months on average, against a 52-month plan
Cambridge Credit Counseling client data: 6,809 enrollments in the year to 30 June 2026, and 1,434 plan completions in 2025. Prepared by Brian Vosburgh, Director of DMP Operations, September 2026.
Your own result depends on your debts, your budget and what your creditors agree to.
Common questions
Does every debt management plan charge the same fees?
No. Fees vary from state to state and from agency to agency because each state sets its own rules for what can be charged.
What fees does Cambridge Credit Counseling charge for a debt management plan?
A debt management plan has a fee to set it up and a monthly fee. Each state sets its own limits, and Cambridge Credit Counseling sets the amount within those limits according to what a household can afford. We explain the fees during your free counseling session, before you decide whether to enroll.
Can fees on a debt management plan be waived?
Past-due and over-limit fees charged by creditors are generally waived for accounts enrolled in a debt management plan, under preset guidelines set by each creditor, not by the counseling agency. In some cases certain accounts may not be eligible for the concessions and benefits.
Will a debt management plan hurt my credit score?
Setting up a debt management plan may adversely affect your credit, though the effect may be temporary as you remain committed to making monthly payments through your Debt Management Plan.
Do I have to enroll in a debt management plan after a counseling session?
No. There is never any obligation to enroll in a debt management plan after a credit counseling session with Cambridge Credit Counseling.
Can the fee be reduced if I cannot afford it?
Yes. Cambridge Credit Counseling sets debt management plan fees according to what a household can afford within the maximum its state allows, and about one client in four has the fee reduced by their counselor for that reason. There is no charge for the counseling session where this is worked out.
Where this information comes from
- Cash-Out Refinancing | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Credit Card Bill Collectors | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Disclosures, State Licenses | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Advice If You Don't Need a DMP | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling, confirmed by President and CEO Christopher Viale in August 2026. Checked 2026-08-24.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Credit Counselors - Housing Counselors | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Financial Literacy | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- What is a Charge-Off? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- How To Get Out of Debt, Federal Trade Commission consumer.ftc.gov Checked 2026-08-28.
- Understanding Credit Reports | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- What is Credit Counseling? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- About Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling compliance guidance Checked 2026-08-07.
- Using Credit Responsibly | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Financial Stress and Your Health | Cambridge Credit cambridge-credit.org Checked 2026-08-04.