
Would it help to talk this through?
A certified counselor will go through your own numbers with you. The session is free and there is nothing to buy.
Cambridge Credit Counseling Is a Nonprofit Agency#
Cambridge Credit Counseling is a 501(c)(3) not-for-profit agency established in 1996 that has provided credit counseling and financial literacy education to consumers nationwide since its founding. Nonprofit status is one factor worth checking when you look into any credit counseling organization.
Free Counseling and a Free Debt Analysis#
Cambridge Credit Counseling offers credit counseling as a free service for consumers who are having trouble paying credit card and other unsecured bills. Before you can find out whether you qualify for a debt management plan, Cambridge Credit Counseling has you complete a personalized, one on one debt analysis with a nationally certified credit counselor, also offered at no cost.
Nationally Certified Counselors#
Cambridge Credit Counseling’s credit counselors are nationally certified. Its staff hold certifications such as NFCC Certified Credit Counselor through the National Foundation for Credit Counseling, HUD-Certified Housing Counselor, HUD-Approved Reverse Mortgage Counselor, and PFE Certified Debt Management Professional through the Partnership for Financial Education.
| Certification | Awarding Body |
|---|---|
| NFCC Certified Credit Counselor | National Foundation for Credit Counseling |
| HUD-Certified Housing Counselor | U.S. Department of Housing and Urban Development |
| HUD-Approved Reverse Mortgage Counselor | U.S. Department of Housing and Urban Development |
| PFE Certified Debt Management Professional | Partnership for Financial Education |
One Payment, Disbursed to Each Creditor#
On a Cambridge Credit Counseling debt management plan, you make one monthly payment to Cambridge Credit Counseling, and Cambridge Credit Counseling disburses individual payments to each of the creditors included in your program. A trustworthy agency should be able to explain this process clearly before you sign up.
| Step | What Happens |
|---|---|
| 1 | Client makes one monthly payment to Cambridge Credit Counseling |
| 2 | Cambridge Credit Counseling disburses individual payments to each creditor on the plan |
Possible Reduction in Interest Rates#
One of the most significant benefits creditors typically extend to clients of a consumer credit counseling agency such as Cambridge Credit Counseling is a reduction in credit card interest rates. On the debts Cambridge Credit Counseling clients bring to a debt management plan, the average interest rate is 28.99 percent, and creditors on the plan typically grant an average rate of 7 percent. On a Cambridge Credit Counseling plan, rate reductions and fee waivers follow preset guidelines set by each creditor, not by us, and in some cases certain accounts may not be eligible for them.
Know the Risks Before You Enroll#
A Cambridge Credit Counseling debt management plan may adversely affect your credit, though the effect may be temporary as you remain committed to making monthly payments through your Debt Management Plan. Not paying your debts could lead creditors to raise finance charges or pursue collection activity, including litigation. Using home equity to pay off credit card debt turns unsecured debt into debt secured by your home, which puts your home at risk. A legitimate agency should be upfront about risks like these, not just the benefits.
What Cambridge Credit Counseling Offers#
- Credit counseling
- Debt management plans
- Housing counseling
- Reverse mortgage counseling
- Bankruptcy counseling
- Student loan debt counseling
- 1st-Time Homebuyer education courses
What to Do Next#
If you want to see whether Cambridge Credit Counseling’s approach fits your situation, you can start with the free credit counseling session and the free one on one debt analysis. A nationally certified counselor will walk through your situation with you before you decide on any next step.
What a debt management plan actually does
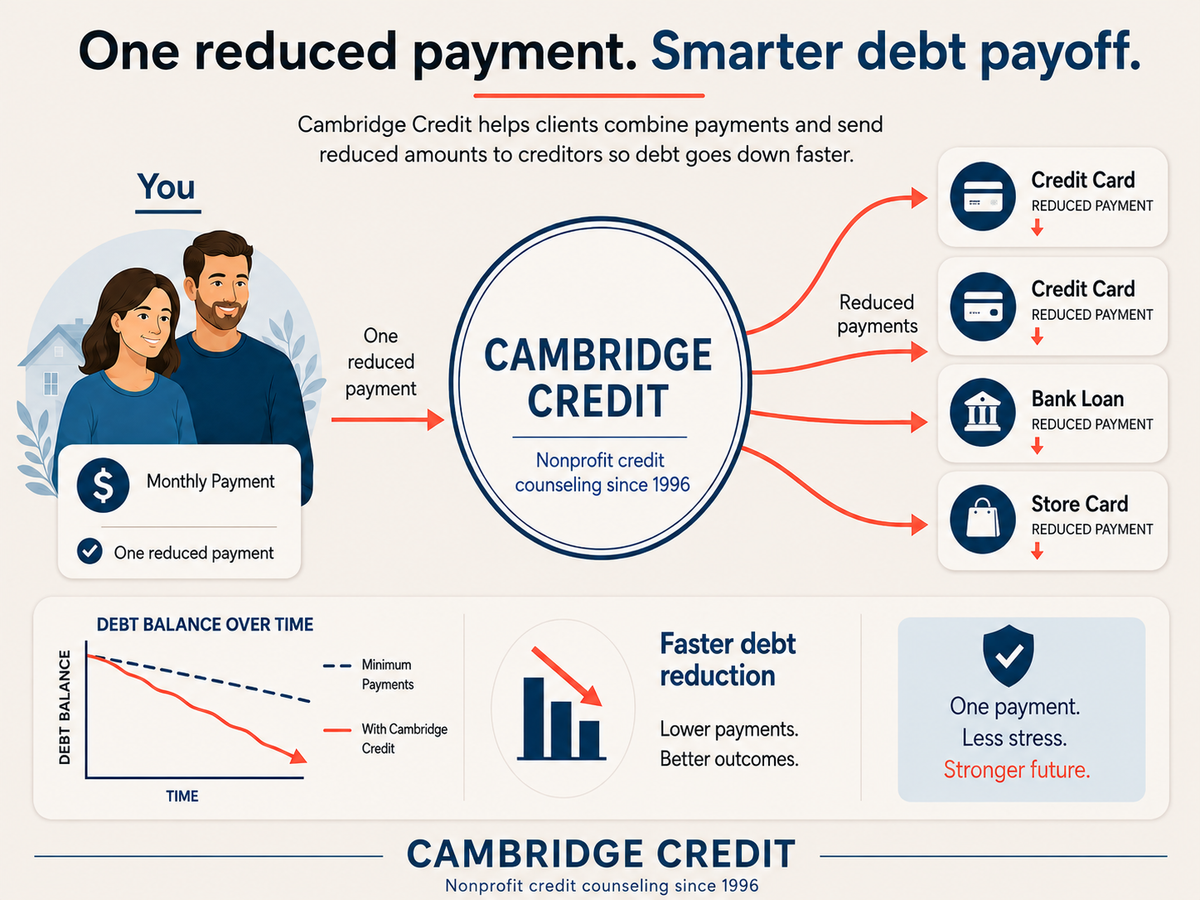
- Interest paidOur typical client would have paid $44,676 in interest on their own, against $4,936 in interest and our fees on the plan
- Interest ratesCreditors cut them from 28.99% to 7% on average
- Monthly payment35.7% lower on average, or 31.1% after our fees
- Time to pay off38 months on average, against a 52-month plan
Cambridge Credit Counseling client data: 6,809 enrollments in the year to 30 June 2026, and 1,434 plan completions in 2025. Prepared by Brian Vosburgh, Director of DMP Operations, September 2026.
Your own result depends on your debts, your budget and what your creditors agree to.
Common questions
Is Cambridge Credit Counseling a nonprofit?
Yes. Cambridge Credit Counseling is a 501(c)(3) not-for-profit agency established in 1996 that has provided credit counseling and financial literacy education to consumers nationwide since its founding.
Does Cambridge Credit Counseling charge for the first session?
No. Cambridge Credit Counseling offers credit counseling as a free service, and it also offers a free one on one debt analysis to help determine whether you qualify for a debt management plan.
Are Cambridge Credit Counseling's counselors certified?
Yes. Cambridge Credit Counseling's counselors are nationally certified, including NFCC Certified Credit Counselor, HUD-Certified Housing Counselor, HUD-Approved Reverse Mortgage Counselor, and PFE Certified Debt Management Professional.
How does the payment process work on a debt management plan?
You make one monthly payment to Cambridge Credit Counseling, and Cambridge Credit Counseling then disburses individual payments to each of the creditors included in your program.
Will my interest rates definitely go down if I enroll?
Not necessarily. Creditors typically extend reduced interest rates to clients of a credit counseling agency such as Cambridge Credit Counseling. On the debts Cambridge Credit Counseling clients bring to a plan, the average rate is 28.99 percent, and creditors on the plan typically grant an average rate of 7 percent. In some cases concessions and benefits can vary based on the level of hardship in the budget. In some cases certain accounts may not be eligible for the concessions and benefits.
Where this information comes from
- Best Credit Counseling Service | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Cash-Out Refinancing | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Disclosures, State Licenses | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Debt Management Plans | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- About Cambridge Credit Counseling cambridge-credit.org Checked 2026-08-04.
- Creating a Household Budget | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Credit Counselors - Housing Counselors | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Credit Counseling Certifications | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Selecting a Consumer Credit Counseling Agency | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Financial Literacy | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Equal Credit Opportunity Act | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- What is Good Credit? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Credit Card Minimum Monthly Payments | Cambridge Credit cambridge-credit.org Checked 2026-08-25.
- How To Get Out of Debt, Federal Trade Commission consumer.ftc.gov Checked 2026-08-28.
- Understanding Credit Card Applications | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- What is Credit Counseling? | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Reestablishing Good Credit | Cambridge Credit cambridge-credit.org Checked 2026-08-04.
- Cambridge Credit Counseling, Marketing Advertisements Source Data, prepared by Brian Vosburgh, Director of DMP Operations, 1 September 2026. Checked 2026-09-02.